Should you get an Amex Cashback Credit Card as an Avios collector?
 Douglas
01 Sep 2026
Last Updated: 29 Sep 2026
Points Pointers
Search for pages and actions
DouglasLast Updated: 29 Sep 2026
If you collect Avios, cashback can feel a little… boring. Every pound you put on a card could be getting you closer to the fun stuff: Business Class, First Class, and flights you’d probably never pay cash for. So why would an Avios collector ever choose cashback?
Because of one main reason: guaranteed value. It's simpler and easier with no reward availability to hunt and no peak-versus-off-peak calculations to run. You spend, earn, and receive money back. End of story, thank you very much.
So then, could an Amex cashback card make sense for an Avios collector? The honest answer is: sometimes, yes. But the question is worth thinking through properly, because the right answer depends entirely on what kind of collector you are.
Below, we’ve explored both Amex cashback cards, worked out what you’d earn with each, and addressed the bigger question of how to get more Avios value from your spending overall.
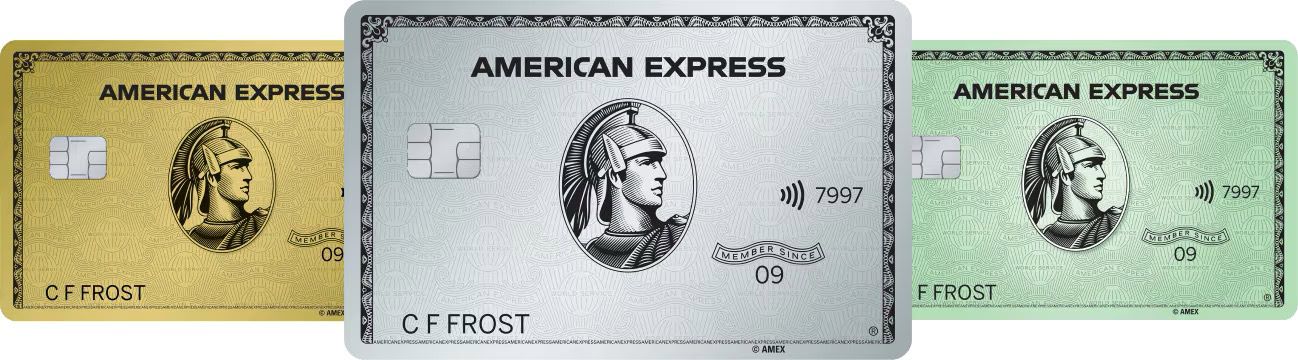
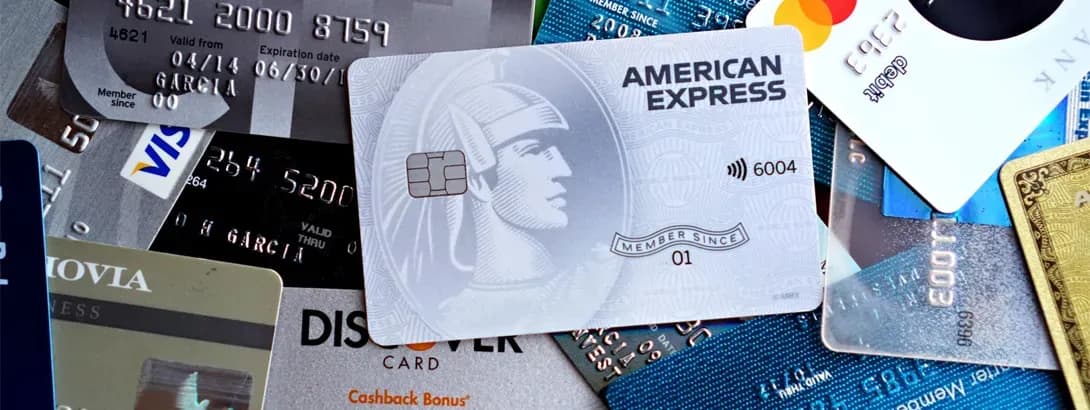
To begin with, let's just line up what we're dealing with and see how they stack up. American Express currently has two cashback cards in the UK.
Here’s what each one looks like:
| Cashback Credit Card | Cashback Everyday | |
|---|---|---|
| Annual fee | £25 | £0 |
| Cashback up to £10,000 | 0.75% | 0.5% |
| Cashback above £10,000 | 1.25% | 1% |
| Sign-up bonus | 5% cashback for the first three months, capped at £125 | 5% cashback for the first five months, capped at £125 |
| Annual cashback cap | None | None |
| Best for | Higher spenders (£10k+) | Lower or moderate spenders |
One important note: the free Cashback Everyday card pays 0.5% on the first £10,000 of spending (not 0.75%), and only pays anything at all if you spend at least £3,000 in the year. You earn nothing if you spend less than that. On the other hand, the paid version has no such threshold, but it requires an upfront annual fee, so keep that in mind when you weigh the two options.
The Platinum Cashback Credit Card offers 5% cashback for the first three months, while the Platinum Cashback Everyday Credit Card offers 5% cashback for the first five months. Both offers are capped at £125 cashback and are only available if you have not held a personal American Express card in the previous 24 months. Most active Amex Avios cardholders will not qualify.
Cashback is paid as a lump-sum statement credit at the end of each card year, not month by month. Worth knowing before you cancel.
The numbers below apply to the paid Cashback Credit Card: 0.75% up to £10,000 and 1.25% above that. The net column deducts the £25 annual fee.
| Annual Spend | Cashback at 0.75% | Cashback at 1.25% (above £10k) | Net (after £25 fee) |
|---|---|---|---|
| £5,000 | £37.50 | N/A | £12.50 |
| £10,000 | £75.00 | N/A | £50.00 |
| £15,000 | £75.00 + £62.50 = £137.50 | £62.50 | £112.50 |
| £20,000 | £75.00 + £125.00 = £200.00 | £125.00 | £175.00 |
| £30,000 | £75.00 + £250.00 = £325.00 | £250.00 | £300.00 |
| £50,000 | £75.00 + £500.00 = £575.00 | £500.00 (above £10k) | £550.00 |
The break-even point between the paid and free cards is £10,000 of annual spending. The free card wins below that, and the paid card edges ahead once the higher rate on spending above £10,000 outweighs the £25 fee. So, right away, that gives you an idea of which type of spender both cards are for.
A word of caution: American Express rounds down the cashback on each individual transaction to the nearest penny. If you spend £3.99 on the free card, you’ll earn 1p rather than the 1.995p the 0.5% headline rate suggests. While that may seem trivial at first, that rounding effect starts making some real changes to your wallet and mood over thousands of small transactions.
The headline cashback rates look simple enough. Where it gets interesting is when you compare them with what an Avios-earning card would produce on the same spending. To keep it fairly broad, there are three types of Avios collectors, and the right answer is different for each.
Let's look at each type:
An Avios-earning card will likely beat a cashback card on the same spend if you regularly redeem points for long-haul Business Class or First Class flights and consistently earn 1p per Avios or more.
At 1 Avios per £1, £10,000 of eligible spending earns 10,000 Avios. If you value each Avios at 1p, that is £100 in redemption value. Outside introductory offers, £10,000 of spending earns £50 on the free Cashback Everyday card, or £75 before the £25 annual fee on the paid Cashback card, leaving £50 net. Avios value is an assumption, not a guaranteed cash return.
The crucial point is that you don’t earn value when you collect Avios. You earn value when you spend it well. An Avios maximiser who never finds reward availability, or who keeps deferring the redemption, is not, in practice, getting 1p per point. They’re getting zero until they book. Cashback, by contrast, lands on your statement whether you plan a holiday or not.
Cashback is likely a stronger argument for these types. If you have 300,000 Avios sitting in your account, cannot find reward availability on the routes you want, and keep adding to the pile without ever spending it down, then another 50,000 points is not worth very much to you in practice. It’s a large number with limited real-world impact.
Cashback is cash. It reduces your statement balance. It does not require you to find a reward seat 355 days out, or to want to fly anywhere in particular, or to remember to check availability at midnight. There’s a strong case to make here: collecting hundreds of thousands of Avios you cannot use is not a strategy. It’s a hobby with no payoff.
If this sounds familiar, a cashback card for some or all of your everyday spending may get you more actual value than earning Avios from American Express ever would on that same spend.
This is probably the most honest recommendation for most readers. Don’t think of it as Avios vs cashback. Think of it as Avios and cashback, depending on what the spending is doing for you at any given moment. Thus, the strategy should be:
That combination approach is more nuanced than treating it as an either-or choice. Choosing when to earn Avios from American Express Membership Rewards cards versus when to take cash is a skill that only practice and frequency would improve. Most of all, it should not be treated as a fixed rule.
This is the right question to ask, and the answer depends on your personal redemption value rather than any theoretical benchmark.
Take £10,000 in spending on a card that earns 1 Avios per £1. That produces 10,000 Avios. What are those worth?
On the same £10,000 spend, outside introductory offers, the free cashback card returns £50 and the paid card returns £75 before its £25 annual fee, also £50 net. At a 1p valuation, 10,000 Avios would be worth £100; at 1.5p, £150; and at 0.5p, £50. These Avios values are assumptions, not guaranteed savings, and interest or other charges can reduce the return.
The problem is that most collectors don’t know their personal redemption value. They assume they’ll redeem well, without checking whether they consistently do. If your Avios are mostly going on short-haul Economy seats at mediocre value, or sitting unredeemed for years, the real-world figure is probably closer to 0.5p than 1p. In that case, the best credit card for collecting Avios may not be delivering the returns you think it is.
That completely changes the calculation, and it’s probably the most important section for most readers of this site. The question is not simply whether an Amex Cashback card earns more than an Avios card on a given spend. The question is what you’re giving up by moving your spending away from an Avios card.
Currently, £15,000 of spending on a BA Amex triggers a Companion Voucher, and its value could vastly outweigh anything a cashback card would return on the same spend. For example, a Companion Voucher used on a Business Class return to New York can be worth well over £1,000 in real-world terms. No cashback card is going to deliver that from £20,000 of spending. Our guide to BA Companion Voucher rules is further reading on voucher use.
The advice here is clear: do not switch your spending to a cashback card mid-year if you’re on course for a Companion Voucher. Finish the threshold first. The calculation changes completely once the Voucher is earned, and that’s a natural point at which to reconsider where your spending should sit.
Once you’ve hit your target, a cashback card for the remainder of the year may make more sense than continuing to earn Avios from an American Express card that’s already delivered its main benefit.
Let's be honest, it can get tiresome playing this never-ending points game. There’s a reason cashback appeals to people who’ve grown tired of the points game. This is for that in-between timeout phase, when you need to stop seeing everything as a purchase to build up your Avios treasure chest. You deserve some downtime. Avios require effort: finding reward availability, understanding the pricing structure, paying taxes and fees, planning around flight schedules, and ultimately wanting to travel at a time when seats are bookable.
Cashback requires none of that. Spend money. Earn cashback. Receive a statement credit at the end of the card year. You do not need a destination, a date, or a redemption strategy, let alone a shortlist of the best Companion Voucher routes.
It’s not glamorous. You cannot fly Business Class to Tokyo with it. But it’s simple, and simplicity has a real value that collectors sometimes underestimate. If you value certainty over potential value, or if your life doesn’t currently revolve around booking holidays based on reward availability, cashback will deliver a more usable return than Avios for the same spending.
Let's make a direct comparison of what a hypothetical Avios collector would get by putting £20,000 through each option. Here it is:
| Scenario | Annual Spend | Reward Value | Notes |
|---|---|---|---|
| BA Amex (1 Avios/£1, valued at 1p) | £20,000 | £200 (20,000 Avios) | Only if well redeemed |
| BA Amex + Companion Voucher hit | £20,000 | £200+ Avios + Voucher | Voucher can be worth £1,000+ |
| Amex Cashback Everyday (free) | £20,000 | £150 (0.5% to £10k, 1% above) | Guaranteed, no planning |
| Amex Cashback Credit Card (£25 fee) | £20,000 | £175 (after £25 fee) | Guaranteed, no planning |
Notice that with £20,000 of annual spending on a BA Amex Premium Plus, you earn the Companion Voucher, which is the card's most valuable benefit by some distance. The points themselves are almost secondary. The cashback options deliver guaranteed, predictable returns, but neither comes close to matching the returns from a well-used Companion Voucher. For a voucher overview, read the BA Companion Voucher rules.
The exception is the collector who’s already earned their Companion Voucher, has no immediate redemption plan, and would otherwise just be accumulating a balance they can’t use. Switching to a cashback card for the rest of the year is a rational, reasonable decision if that’s the case.
So, to summarise all that we've covered, a cashback Amex makes sense if:
An Avios card wins if:
Should an Avios collector get an Amex Cashback card? Sometimes, more is better, and in that spirit, the answer is that you shouldn't choose one option over the other. In fact, the best strategy is one that uses a little bit of both, depending on your needs and circumstances, because, to be fair, the right credit card Avios strategy is rarely one-size-fits-all, and you're better off by hedging your bets.
An Avios card will almost certainly deliver more over the long run if you’re a serious collector with a clear redemption plan, a Companion Voucher in play, and a track record of extracting good value from your points. The best credit card for collecting Avios is still a BA Amex or an equivalent when it works hard for you.
You do not need to choose one card type forever. Prioritise Avios when you have a clear redemption or voucher target, then use cashback when certainty matters more.